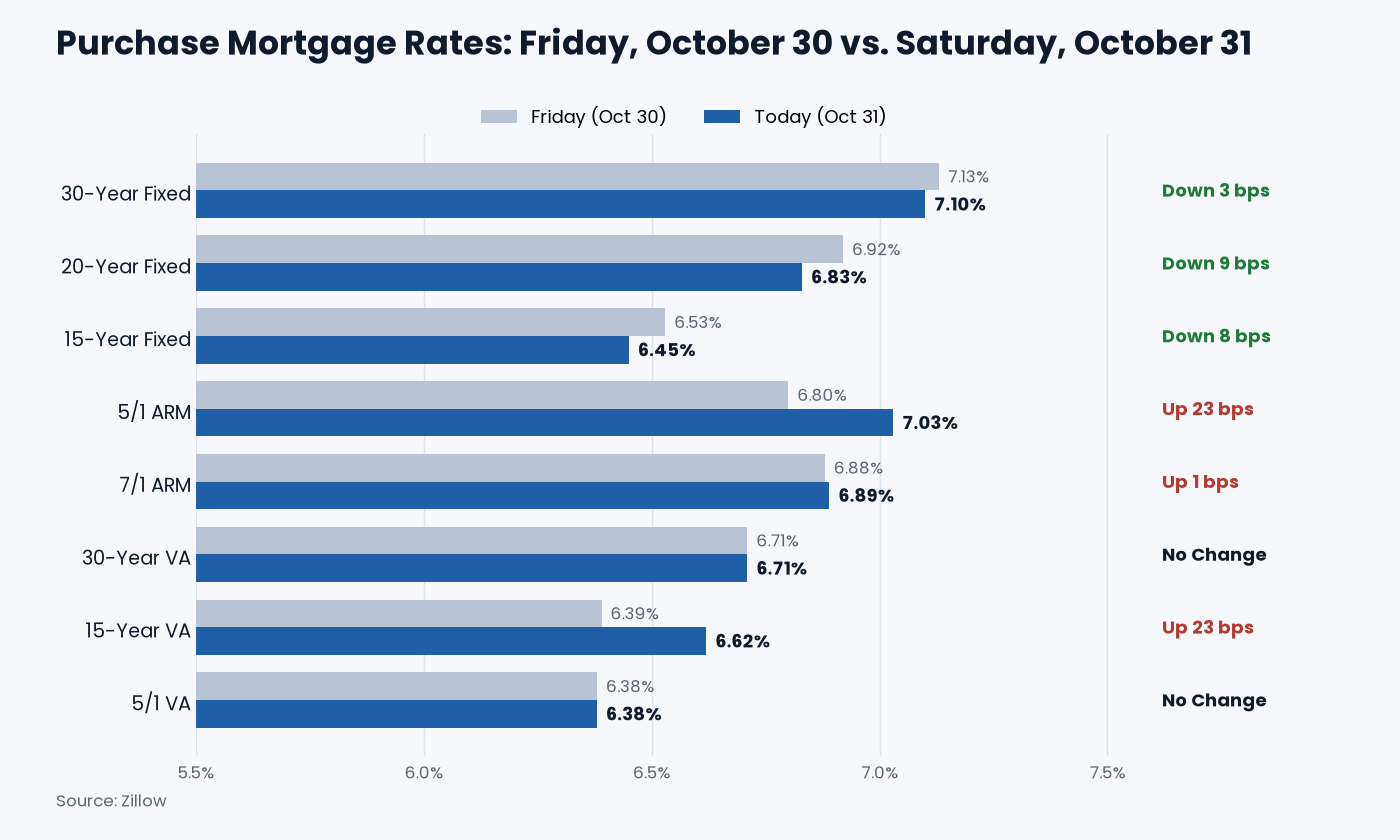
Fixed-rate buyers got a little more good news to close out October. As of Saturday, October 31, 2026, Zillow’s average 15-year fixed purchase rate dropped to 6.45%, down 8 basis points from Friday’s 6.53%. The 20-year fixed fell even more, sliding 9 basis points to 6.83%, and the popular 30-year fixed eased 3 basis points to 7.10%.
Adjustable loans moved the other way. The 5/1 ARM jumped 23 basis points to 7.03%, giving back the big drop it made the day before. The 7/1 ARM barely changed at 6.89%, so it is now the cheaper of the two ARMs. On the VA side, the 30-year VA and the 5/1 VA held flat, while the 15-year VA rose 23 basis points to 6.62%.
So the short answer is this: if you want a fixed rate, Saturday’s numbers are a bit kinder than Friday’s. If you were eyeing a 5/1 ARM because of yesterday’s dip, that window has mostly closed. Below is the full rate table, what the changes mean in real dollars, and how to pick a loan that fits your plans.
Today’s Mortgage Rates, October 31: 15-Year Fixed Drops to 6.45% as 5/1 ARM Jumps Back Above 7%
Zillow Purchase Rates for Saturday, October 31, 2026
Here are today’s national average purchase rates next to Friday’s numbers:
| Loan Type | Saturday (Oct 31) | Friday (Oct 30) | Change |
|---|---|---|---|
| 30-year fixed | 7.10% | 7.13% | Down 3 bps |
| 20-year fixed | 6.83% | 6.92% | Down 9 bps |
| 15-year fixed | 6.45% | 6.53% | Down 8 bps |
| 5/1 ARM | 7.03% | 6.80% | Up 23 bps |
| 7/1 ARM | 6.89% | 6.88% | Up 1 bp |
| 30-year VA | 6.71% | 6.71% | No change |
| 15-year VA | 6.62% | 6.39% | Up 23 bps |
| 5/1 VA | 6.38% | 6.38% | No change |
Source: Zillow
What stands out on the board today:
- All three conventional fixed rates fell. The 30-year, 20-year and 15-year fixed each came down at the same time.
- The 5/1 ARM lost its edge. At 7.03%, it sits just 7 basis points under the 30-year fixed.
- The 7/1 ARM is now the better adjustable deal. It is 14 basis points below the 5/1 ARM and gives you two more years before any reset.
- The 5/1 VA is still the lowest rate on the list at 6.38%.
Quick refresher: one basis point is 0.01%. An 8 basis point drop means the rate fell by 0.08 of a percentage point.

Why the 15-Year Fixed Drop Matters
The 15-year fixed is the loan for people who want to own their home free and clear sooner. Its payment is higher each month, but you pay far less interest overall. Today’s drop to 6.45% makes that trade a little easier.
On a $400,000 loan, a 15-year fixed at 6.45% costs about $3,473 a month for principal and interest. At Friday’s 6.53%, it was about $3,491. That’s roughly $18 less per month. It sounds small, but over the full 15 years it trims total interest by about $3,200.
The gap between the 15-year and the 30-year is now 65 basis points. That’s a healthy discount for choosing the shorter term.
Monthly Payment Changes on a $400,000 Loan
Here’s how today’s rates change the principal-and-interest payment compared with Friday. These are Norada estimates based on Zillow’s average rates, and they leave out taxes, insurance and any mortgage insurance.
| Loan Type | Friday Payment | Saturday Payment | Difference |
|---|---|---|---|
| 30-year fixed | $2,696 | $2,688 | $8 less |
| 20-year fixed | $3,082 | $3,061 | $21 less |
| 15-year fixed | $3,491 | $3,473 | $18 less |
| 5/1 ARM | $2,608 | $2,669 | $61 more (first five years) |
| 7/1 ARM | $2,629 | $2,632 | $3 more (first seven years) |
Payment figures are Norada estimates.
If you locked a 5/1 ARM on Friday, give yourself a pat on the back. If you’re shopping today, the 5/1 ARM payment is only about $19 a month below the 30-year fixed, which is a thin reward for taking on reset risk.
The 5/1 ARM Bounced Right Back
Friday’s 30 basis point plunge in the 5/1 ARM didn’t last. Saturday’s 23 basis point jump erased most of it. As these two days show, daily ARM averages can swing much more than fixed rates.
The lesson here is simple. Don’t build your whole plan around one day’s ARM number. If an adjustable loan fits your life, compare it with the 30-year fixed on the day you’re ready to lock, not the day you first saw a good headline.
The 7/1 ARM Takes the Lead
For buyers who still like the idea of an adjustable loan, the 7/1 ARM looks like the better pick today. At 6.89%, it’s 21 basis points below the 30-year fixed. On $400,000, that’s about $56 less per month, or roughly $4,700 over the seven fixed years (a Norada estimate).
Seven years is also a longer runway. Many people sell, move or refinance well before then, so the reset may never touch them. Just make sure you know your caps and your worst-case payment before you sign.
VA Loans: Steady, With One Exception
The 30-year VA rate held at 6.71%, which is 39 basis points below the conventional 30-year fixed. That works out to about $104 less per month on a $400,000 loan.
The odd one out was the 15-year VA, which climbed to 6.62%. That’s now 17 basis points above the conventional 15-year fixed. A 15-year VA loan at today’s rate costs about $3,511 a month, versus about $3,473 for a conventional 15-year. If you’re eligible for VA benefits and want a short term, ask lenders to quote both, because today the conventional loan may come out ahead on rate.
Where Rates Are Headed
Freddie Mac’s weekly survey on Thursday showed the average 30-year rate at 7.24%, its lowest level this month. Zillow’s daily 30-year fixed has also edged lower two days in a row, from 7.15% on Thursday to 7.10% today.
Zillow’s own economists don’t expect a fast slide from here. In its October 28 mortgage rate outlook, Zillow said it expects rates to “ease only gradually, remaining at 7% or higher for the rest of 2026 and 6.5% or higher in 2027.” Zillow also estimated that waiting a year to buy would trim just $26 off a typical monthly payment, because home values are expected to keep rising.
In plain terms, waiting for a big rate drop may not pay off much. Buying when you’re ready, at a payment you can handle, usually matters more than catching the perfect rate.
Which Loan Fits You Best?
A 15-year or 20-year fixed may suit you if:
- You can comfortably handle a higher monthly payment.
- You want to save a large amount of interest over the life of the loan.
- You’d like to be mortgage-free before retirement or before the kids reach college.
A 30-year fixed may suit you if:
- You want the lowest fixed payment and plenty of breathing room in your budget.
- You plan to stay in the home for a long time.
- You’d like the option to refinance later if rates fall further.
A 7/1 ARM may suit you if:
- You expect to move, sell or refinance within about seven years.
- You could still afford the payment if the rate rose after the fixed period.
Smart Moves Before You Lock
- Get at least three quotes on the same day. That’s the only fair way to compare lenders.
- Look at the APR, not only the rate. The APR rolls in fees and points.
- Ask about lock length and cost. A longer lock can cost more, so match it to your closing date.
- Check your credit first. Even a small bump in your score can lower the rate you’re offered.
My Take for Saturday Shoppers
Saturday was a good day for fixed-rate buyers. The 15-year fixed fell to 6.45%, the 20-year fixed dropped to 6.83%, and the 30-year fixed edged down to 7.10%. Meanwhile, the 5/1 ARM gave back most of Friday’s gain, so the adjustable advantage has narrowed.
Over the years, I’ve noticed that the buyers who feel best about their loan aren’t the ones who timed the market perfectly. They’re the ones who picked a payment they could live with. Start there, then let the rate table help you choose the term.
Rates move every day, so treat these numbers as a snapshot of Saturday, October 31, 2026. Your actual rate will depend on your credit score, down payment, loan size and lender, so get a personalized quote before making a decision.
Read More:
Explore these related articles for even more insights: