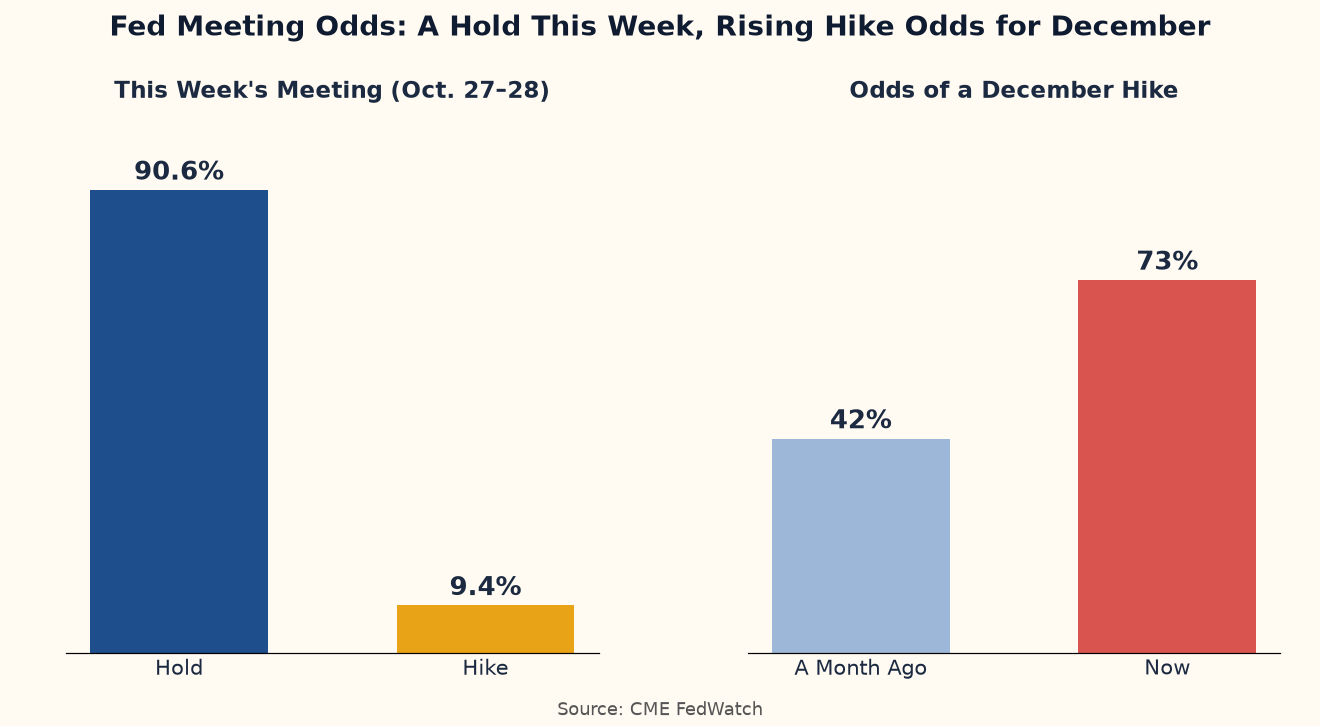
Will interest rates go up again? Probably not this week, but a December hike looks more likely by the day. The Fed meeting begins today, Tuesday, October 27, and the decision lands on Wednesday, October 28, at 2:00 p.m. Eastern Time. Traders using the CME FedWatch tool put the chance of a hold at about 90.6%, which would keep the federal funds rate at 3.75% to 4.00%. The odds of a quarter-point hike this week are only about 9.4%.
The bigger story is what comes next. The odds of a hike at the December 8–9 meeting have jumped to about 73%, up from roughly 42% a month ago. Inflation got hotter in September, and the Fed already raised rates once this fall. So if you’re borrowing money, buying a home, or keeping cash in savings, this two-day meeting is worth a few minutes of your attention.
Below, I’ll walk you through why the Fed is likely to sit tight for now, why another increase is still on the table, and what each outcome could mean for your mortgage, your credit card, and your bank account.
Fed Meeting Begins Today: Will Interest Rates Go Up Again Before Year-End?
Here’s the honest answer in plain words. A pause this week is the most likely result. But the Fed is leaning toward higher rates, not lower ones, and many experts expect it to raise rates one more time before 2026 is over.
A Quick Look Back: The September Surprise
At its September meeting, the Fed raised its benchmark rate by a quarter point, to today’s range of 3.75% to 4.00%. That was the first hike in more than three years. For a long stretch before that, borrowers were hoping for cuts. September flipped the script.
Why does that matter now? Because the Fed rarely moves in giant leaps. It often raises rates, waits to see how the economy reacts, and then decides whether to go again. This week looks like one of those “wait and see” moments.
What the Market Odds Are Telling Us
Traders bet on Fed moves through futures contracts, and the CME FedWatch tool turns those bets into simple odds. Think of it like a weather forecast for interest rates. It isn’t a promise, but it tells you which way the wind is blowing.
Right now, the forecast for this week is calm. Odds of a hike this week were 10.5% on Monday afternoon, down from 33.8% on October 14, according to InvestmentNews. So the fear of a surprise move this week has cooled off.
December is a different picture. The chance of a hike at that meeting has climbed from about 42% to about 73% in a month. InvestmentNews also puts the odds of at least one hike by the end of the year at more than 80%.

Why Inflation Keeps the Fed on Edge
The Fed has two big jobs: keep prices steady and keep people working. When prices rise too fast, raising rates is its main tool to cool things down.
The latest numbers aren’t helping. Consumer prices rose 3.7% over the past year in September, up from 3.4% in August. That’s moving in the wrong direction, and well above the Fed’s long-run goal of 2%. When inflation speeds up like this, the Fed gets nervous about waiting too long.
What the Experts Expect
Most analysts see a pause this week with a strong warning attached. Here’s what a few of them are saying:
- Aditya Bhave, economist at BofA Securities, told Kiplinger: “The inflation picture has gotten worse on net since the September meeting.” He thinks the case for raising rates now is real.
- Paul Eitelman, global chief investment strategist at Russell Investments, told Kiplinger: “We expect a hawkish hold in October with the Fed delivering one more hike at year-end.”
- Melissa Cohn of William Raveis Mortgage pointed out to InvestmentNews: “It’s a week before the election.” She expects a hold this week, and she thinks the Fed should raise rates in December if oil prices keep soaring.
A “hawkish hold” simply means the Fed keeps rates the same but signals that it’s ready to raise them later. Picture a parent who doesn’t take away the car keys today but makes it very clear that one more late night will do it.
The Election Factor
The midterm elections are on November 3, just days after this meeting. The Fed says it doesn’t make decisions based on politics. Still, a big surprise move a week before voters head to the polls would draw a lot of heat. That’s one more reason many people expect Fed Chair Kevin Warsh and his colleagues to stay put now and save any hike for December, once the votes are counted and more data is in.
How a Rate Hike Could Reach Your Mortgage
Here’s a point that trips up a lot of people. The Fed doesn’t set mortgage rates directly. Mortgage rates tend to follow the 10-year Treasury yield, which moves on what investors expect from inflation and the Fed over many years.
Before the stock market opened on October 27, Kiplinger reported the 10-year yield at 4.995%, right at the doorstep of 5%. The 2-year sat at 4.735%, and the 30-year at 5.302%. Those are high levels, and they help explain why home loans still feel expensive. According to Zillow, the average 30-year fixed mortgage rate rose to 7.23% today. You can see the full breakdown in our latest mortgage rates update.
So even if the Fed holds this week, a tough message about December could push yields, and mortgage rates, a bit higher. A softer tone could do the opposite.
What It Means for You
Here’s how the two paths could play out for everyday money decisions:
- Homebuyers: If you’ve found the right home and the payment fits your budget, don’t sit on the sidelines waiting for a big rate drop. The odds point the other way for now. Get a rate lock quote, and ask your lender how long the lock lasts.
- Homeowners with an adjustable-rate loan or a HELOC: These rates often move soon after the Fed. A December hike could raise your payment. Now is a good time to look at fixing the rate or paying down the balance.
- Credit card users: Card rates usually follow the Fed’s rate closely. Paying down high-interest balances before December is one of the smartest moves you can make.
- Savers: Good news here. High-yield savings accounts and CDs keep paying solid returns while rates stay high, and another hike could nudge them up a little more.
What to Watch on Wednesday
The decision comes out at 2:00 p.m. ET on Wednesday, and the chair’s press conference typically starts at 2:30 p.m. ET. Three things are worth listening for:
- The wording of the statement. Watch for any phrase that hints more increases may be needed.
- How the chair talks about inflation. If he sounds worried about September’s jump, December odds could climb even higher.
- Any dissent. If one or more members vote for a hike this week, that’s a strong sign the next move is up.
My Take
I don’t expect rates to go up this week. But I wouldn’t plan your finances around rates coming down soon, either. With inflation at 3.7% and the market leaning hard toward a December hike, the safer bet is that borrowing stays pricey through the end of the year.
That doesn’t mean you should freeze. A home you can comfortably afford today is still a good home. Just build your budget around today’s rates, not hoped-for ones, and keep some room for a slightly higher payment if you have a variable-rate loan. We’ll be watching Wednesday’s announcement closely and will share what it means for you as soon as it’s out.
Read More:
Explore these related articles for even more insights: