Today’s mortgage rates bring another break for buyers: on Saturday, November 7, 2026, the 30-year fixed purchase rate is 6.86%, down 24 basis points from last week and 13 basis points from Friday. That’s Zillow’s national average as reported by Yahoo Finance. The weekly drop is the comparison behind today’s headline, not a single-day fall. The 15-year fixed and 5/1 ARM purchase averages are also lower over both periods.
Lower rates give you a better starting point, but they don’t make every house affordable. The useful question is whether a lender’s actual offer fits your budget after taxes, insurance, and other costs. Here is today’s full picture and how to put it to work without stretching too far.
Today’s Mortgage Rates, November 7: 30-Year Fixed Falls 24 Basis Points to 6.86%
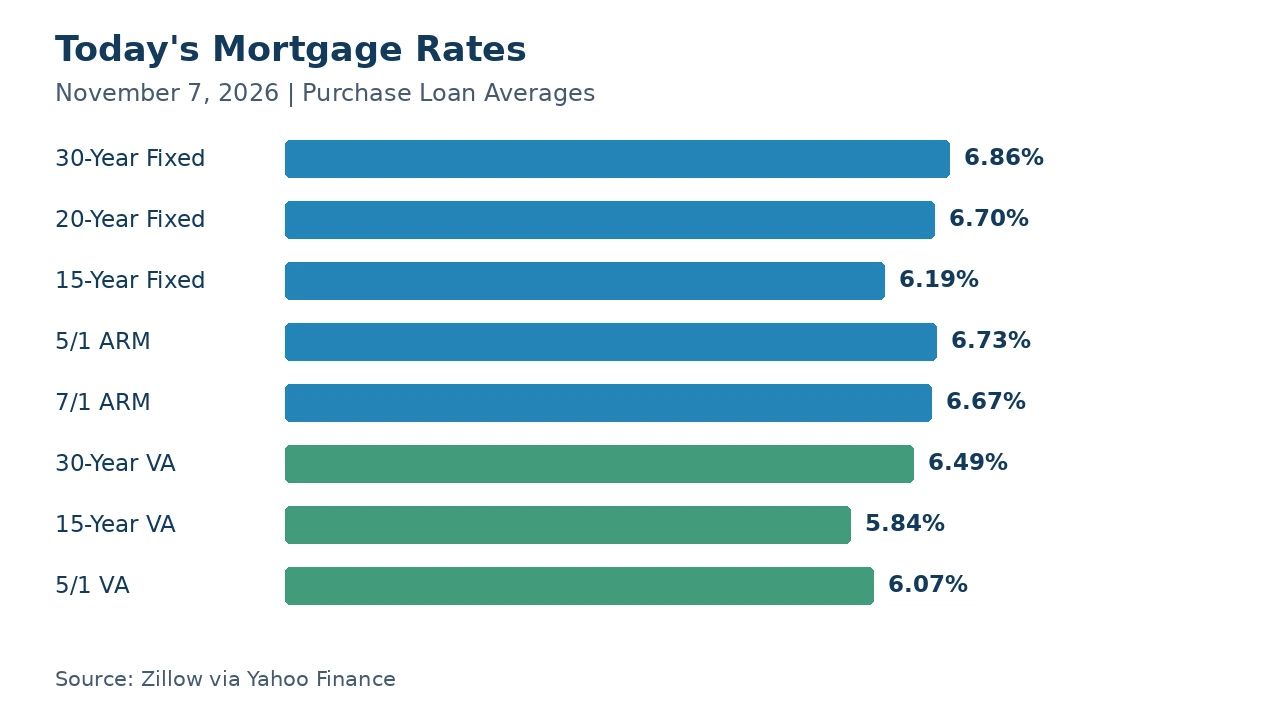
Today’s Purchase Mortgage Rates
These are the Zillow purchase averages supplied to Yahoo Finance for Saturday, November 7, 2026. Treat them as a shopping guide, not a promise that a lender will offer you the same price.
| Loan Type | Rate |
|---|---|
| 30-Year Fixed | 6.86% |
| 20-Year Fixed | 6.70% |
| 15-Year Fixed | 6.19% |
| 5/1 ARM | 6.73% |
| 7/1 ARM | 6.67% |
| 30-Year VA | 6.49% |
| 15-Year VA | 5.84% |
| 5/1 VA | 6.07% |
Source: Zillow via Yahoo Finance.
The loan term matters as much as the rate. A shorter fixed loan gives you less time to repay the balance. An adjustable-rate mortgage, or ARM, starts with a set rate period and can change later. Compare those features before picking the smallest number in the table.

What Changed Since Friday and Last Week?
The 30-year fixed is down 13 basis points from Friday and 24 basis points from last week. The 15-year fixed stands at 6.19%, down 16 basis points from yesterday and 26 basis points over the week. The 5/1 ARM is 6.73%, down 7 basis points from Friday and 30 basis points from last week.
A basis point is a small unit used to describe a rate change. It keeps a change in the rate separate from a percent change in the payment. Here, the weekly declines tell us borrowing costs eased for these loan types. They do not tell us what rates will do when lenders next update their offers.
Why the 30-Year Fixed Still Deserves Attention
The appeal of a 30-year fixed loan is simple: the interest rate stays the same through the loan’s term. Your principal-and-interest payment is steady, which helps with planning. Taxes and insurance can still change, so the full monthly housing bill is not frozen.
At 6.86%, today’s average gives buyers a lower rate to compare against than Friday’s reading. If you already have a quote, ask the lender to refresh it before you make a choice. An older worksheet may no longer reflect the lender’s current pricing. If you have locked, ask about the terms of that lock rather than assuming the rate will fall automatically.
Could a Shorter Fixed Loan Fit Your Budget?
The 15-year fixed rate is 6.19%, while the 20-year fixed is 6.70%. Both deserve a look if you want to pay off the home sooner. But a lower rate does not mean a lower monthly payment when the repayment period is shorter.
Ask for payment quotes on the same loan balance, with the same down payment and fee assumptions. Then check what is left after the mortgage, groceries, transport, savings, and repairs. A fast payoff is useful only if the monthly bill leaves enough breathing room. You do not want to trade a smaller interest bill for a budget that breaks whenever something goes wrong.
Read the ARM Terms Before Choosing the Rate
Today’s 5/1 ARM average is 6.73%, and the 7/1 ARM average is 6.67%. Those opening rates may catch your eye, but they are not fixed for the full life of the loan. The initial fixed period ends, and later adjustments follow the loan’s rules.
Ask the lender to explain the adjustment schedule, the index, the margin, and the caps in plain language. More important, ask what the payment could become if the rate rises. Planning to move or refinance is not a guarantee that either will be easy. Choose an ARM only if you can live with its risks, not because you need a future refinance to rescue the payment.
VA Borrowers Have Their Own Rate Options
The VA averages in today’s report are 6.49% for a 30-year loan, 5.84% for a 15-year loan, and 6.07% for a 5/1 adjustable loan. Eligible borrowers should ask for VA quotes alongside other options that fit their needs.
Keep the comparison fair. Ask about lender fees, any applicable VA funding fee, and the total cash needed to close. A quoted rate alone does not show the whole cost. Also make sure each offer uses the same lock period. You want to know which loan works best for your household, not merely which advertisement has the lowest headline.
Today’s Refinance Rates From the Same Report
Yahoo Finance also reported these Zillow refinance averages. They belong to the same report as the purchase figures above; they should not be mixed with another rate series or presented as purchase rates.
| Refinance Loan | Rate | Drop From Last Week |
|---|---|---|
| 30-Year Fixed | 6.88% | 18 Basis Points |
| 15-Year Fixed | 6.35% | 13 Basis Points |
| 5/1 ARM | 6.61% | 17 Basis Points |
Source: Zillow via Yahoo Finance.
For homeowners, the key comparison is with your current loan. Ask for closing costs and monthly savings in writing. Divide the costs by the savings to estimate how long it takes to recover the expense. Also check whether the new term stretches repayment further into the future. A smaller payment can feel good while still leaving you paying interest longer.
Should You Lock or Keep Watching?
A falling weekly average makes waiting tempting. Still, the right answer depends more on your closing date and budget than on a guess about the next headline. A lock protects a quoted rate for a set period under the lender’s terms. It does not promise you the lowest possible rate.
- Consider locking: Your closing is near, the full payment is comfortable, and a higher rate would put the purchase at risk.
- Consider watching: Your timeline is flexible, you understand the risk of a rebound, and your budget has room for it.
- Ask about a float-down: Find out whether your lender allows a lower rate after locking, what it costs, and which conditions apply.
Make Your Lender Quotes Easy to Compare
Give each lender the same loan details and ask for written quotes close together in time. Your credit, loan size, down payment, property, and loan type all affect the offer. National averages cannot account for those personal details.
Look at the interest rate, APR, points, lender fees, and cash to close. Points are upfront costs paid for a lower rate, so a cheaper advertised rate may come with a bigger bill at closing. Ask for an option without points as well. That makes it easier to see what you are paying for and whether the tradeoff suits your plans.
Keep Some Cash Beyond the Down Payment
A lower mortgage rate can help, but it should not be a reason to spend every dollar you have saved. Homeownership brings bills that do not arrive on a neat monthly schedule. A repair, a move, or a gap in income can put pressure on a budget that looked fine on paper.
Before raising your offer price, decide what cash you want left after closing. Include moving costs and any work the home needs right away. Ask about property taxes, homeowners insurance, and association dues before treating the lender’s payment estimate as your full housing cost.
This is especially important if today’s lower rate makes a more expensive home look just within reach. A little room in the budget can be worth more than an extra room in the house. Let the rate drop improve your margin of safety first.
The Bottom Line for Saturday
The useful news today is a real weekly drop: the 30-year fixed purchase average is 6.86%, down 24 basis points from last week. Friday’s comparison is also lower, by 13 basis points. That improves the starting point for a loan conversation, without promising another decline tomorrow.
Use the calculator below to test your own price and down payment. Then add the costs the loan payment leaves out. If the complete budget works and the home fits your needs, you can make a decision based on your life rather than trying to call the exact bottom in rates.
Estimate Your Monthly Mortgage Payment
Estimates only. Your actual payment depends on your lender, taxes and insurance.
Estimated Monthly Payment
$0
- Principal & Interest$0
- Property Tax$0
- Home Insurance$0
- PMI$0
- HOA$0
$0Loan Amount
$0Total Interest
$0Total Cost of Loan
Read More:
Explore these related articles for even more insights: