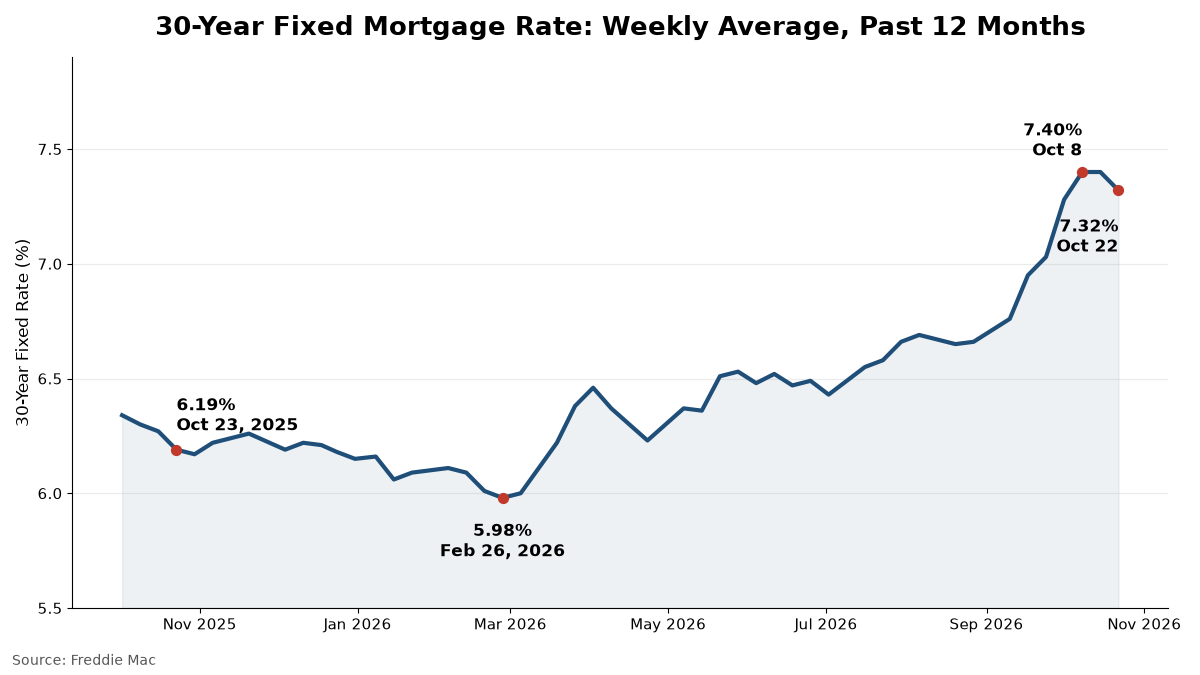
Mortgage rates are likely to stay near 7% for most of the next two years, and the big forecasters no longer expect a quick return to 6%. According to Freddie Mac, the average 30-year fixed rate was 7.32% on Oct. 22, 2026, up from 6.19% a year earlier. The latest outlooks from Fannie Mae, the Mortgage Bankers Association and Wells Fargo put the rate between about 6.9% and 7.5% through 2027, with MBA, the only one of the three that goes out to 2028, seeing just 7.0% by the end of 2028.
That is a big shift from the start of this year, when many buyers expected cheaper loans. Here are the latest mortgage rate predictions for the next 2 years, why they changed so fast, and what they mean for your budget.
Mortgage Rate Predictions for the Next 2 Years: 2026–2028
Where Mortgage Rates Stand Right Now
Rates have had a wild year. The 30-year fixed rate fell to 5.98% on Feb. 26, 2026, its first reading below 6% since 2022. Then it climbed for months, crossed 7% in late September, and hit 7.40% in the weeks ending Oct. 8 and Oct. 15.
This week brought a small break. The Freddie Mac weekly survey showed the 30-year rate easing to 7.32%, while the 15-year fixed rate slipped to 6.68%. One down week is welcome, but rates are still more than a full point higher than they were a year ago.

Why Rates Jumped This Fall
Three things pushed mortgage rates up quickly.
- The Fed started raising rates again. On Sept. 16, 2026, the Federal Reserve raised its benchmark rate by a quarter point to a range of 3.75% to 4%. It was a 12-0 vote, and the Fed said it wanted to bring inflation back to its 2% goal faster.
- Bond yields surged. Mortgage rates tend to follow the 10-year Treasury yield. Treasury Department data shows the 10-year yield closed at 5.31% on Oct. 5, 2026, its highest close this year. A year earlier, on Oct. 22, 2025, it was 3.97%.
- Inflation and oil. Higher energy prices tied to the conflict with Iran have kept inflation elevated, which makes lenders and bond investors demand higher rates.
There is one hopeful sign. The 10-year yield dropped to 4.96% on Oct. 22, its first close below 5% since Sept. 22. If that holds, mortgage rates could drift a little lower in the weeks ahead.
What the Latest Forecasts Say
Forecasts moved sharply higher this fall. Here is how the three biggest published forecasts compare. Note that each one covers a different time frame.
Fannie Mae: 7.4% This Quarter, 7.5% All of 2027
Fannie Mae’s economists made the biggest change. Their October 2026 housing forecast, dated Oct. 12, expects the 30-year rate to average 7.4% in the fourth quarter of 2026 and 7.5% in every quarter of 2027. That is a big upward revision from their September outlook.
Their forecast runs only through the end of 2027, and it is based on rates as of Sept. 30, before this month’s run to 7.40%.
MBA: Above 7% Through 2027, 7.0% by Late 2028
The Mortgage Bankers Association’s Mortgage Finance Forecast, released Oct. 11, is the only one of the three that reaches 2028. It sees the 30-year rate averaging:
- 7.3% in the fourth quarter of 2026
- 7.2% in the first three quarters of 2027, then 7.1% at the end of 2027
- 7.1% in early 2028, easing to 7.0% by the end of 2028
MBA also expects the 10-year Treasury yield to average 5.1% this quarter, about 5.0% for most of 2027 and 4.9% through 2028. That is why its mortgage forecast barely moves. MBA’s table even shows 6.9% for the end of 2029.
Wells Fargo: A Slow Slide Below 7% in 2027
The Wells Fargo Economics outlook, dated Oct. 15, is a bit more hopeful. It shows the conventional mortgage rate at 7.10% at the end of 2026, then 7.05%, 7.00%, 6.95% and 6.90% at the end of each quarter of 2027. That works out to an average of 6.98% for 2027. Its forecast also stops at the end of 2027.
Wells Fargo expects the Fed to raise rates once more in December and then hold its benchmark at 4% to 4.25% through 2027. It also says the risks lean toward more hikes, not fewer.

Home Builders and Realtors Agree: No Quick Relief
Two other big housing groups have not published new year-by-year rate numbers, but their comments point the same way.
- Home builders: On an Oct. 9 podcast from the National Association of Home Builders, chief economist Robert Dietz said, “Unfortunately, I think this 7.5% range [for mortgage rates] is the new normal until we get a resolution on these geopolitical factors.”
- Realtors: National Association of Realtors chief economist Lawrence Yun had expected rates to average around 6.5% this year. As Realtor.com reported on Oct. 21, he now says, “If somehow at the beginning of 2027 we see mortgage rates closer to 6%, we will see good buying activity at that time.” For now, that is a hope, not a forecast.
Putting the Forecasts Together: The Next 2 Years
Put the forecasts side by side and a clear picture shows up.
- Late 2026: All three forecasts cluster between 7.1% and 7.4%. Expect rates to stay around 7% for the rest of this year.
- 2027: The range is roughly 6.9% to 7.5%. Even the most hopeful forecast, from Wells Fargo, only gets just under 7% by the end of next year.
- 2028: Only MBA goes this far, and it sees about 7.0%. A drop back to 6% is not in any of these published numbers.
In plain words: the forecasters see rates leveling off near 7%, not falling sharply. Rates can still swing up or down by a quarter point or more in a few weeks, so treat these numbers as a guide, not a promise.
What Could Push Rates Lower or Higher
Forecasts change, and October proved how fast that can happen. Watch these signals.
Rates could fall faster if:
- Inflation cools and the Fed stops raising rates sooner than expected.
- The 10-year Treasury yield keeps falling below 5%.
- Oil prices drop and tension with Iran eases.
- The economy slows sharply. NAHB’s Dietz puts the chance of a broad pullback next year at 35%, and slowdowns usually bring lower rates.
Rates could rise further if:
- Inflation stays hot and the Fed hikes more than once more.
- Government borrowing keeps pushing bond yields up.
- Energy prices climb again.
The next big test comes soon. The Fed meets on Oct. 27-28, and again on Dec. 8-9.
What This Means for Your Monthly Payment
Small rate changes add up. Here is the monthly principal and interest on a $400,000, 30-year loan at the rates in these forecasts:
| Rate | Monthly Payment | Where This Rate Comes From |
|---|---|---|
| 6.19% | $2,447 | One year ago |
| 6.90% | $2,634 | Wells Fargo, end of 2027 |
| 7.00% | $2,661 | MBA, end of 2028 |
| 7.32% | $2,748 | Today |
| 7.50% | $2,797 | Fannie Mae, all of 2027 |
Compared with a year ago, today’s rate adds about $300 a month on that loan. If Wells Fargo is right and rates dip to 6.90% by late 2027, you would save about $114 a month compared with today. That’s helpful, but it’s not a big drop.
Should You Buy Now or Wait?
There is no perfect answer, but these forecasts help you plan.
Buying now may make sense if:
- You found a home that fits your budget at today’s rate, not a guessed future rate.
- You plan to stay at least five to seven years.
- You can negotiate seller credits to buy down your rate, which is more common when homes sit longer.
Waiting may make sense if:
- The payment at 7% or more would stretch you too thin.
- You need time to raise your credit score or save a bigger down payment.
- Your job or income is uncertain right now.
Whatever you decide, shop with at least three lenders. Rates offered on the same day can differ by a meaningful amount, and that gap can matter more than waiting a few months.
The bottom line: the experts expect mortgage rates to stay close to 7% through 2027 and into 2028. Plan your home purchase around that reality, and treat any drop below it as a bonus.